JM Financial on Wednesday said it had a "careful and detailed review" of the Reserve Bank's order imposing restrictions on the company's financing business and asserted that there was "no material deficiencies" in its loan sanctioning process. The Reserve Bank on Tuesday imposed restrictions on JM Financial Products Ltd after it found the company indulged in various manipulations, including repeatedly helping a group of its customers to bid for various IPOs (initial public offerings) by using loaned funds. "After careful and detailed review of the order issued by the RBI on the action against JM Financial Products Ltd, we strongly believe that there have been no material deficiencies in our loan sanctioning process.
Towards the end of February, the Reserve Bank of India (RBI) restored the risk weighting on banks loans to non-banking financial companies (NBFCs; including to microfinance institutions, or MFIs) to 100 - back to its November 2023 position - from 125. It is only a partial relief though. "Higher risk weighting on unsecured lending continues to be in place while the same on bank funding to NBFCs has been done away with. "This is a positive step by RBI," says Rajiv Sabharwal, managing director (MD) and chief executive officer (CEO), Tata Capital.
Moody's Investors Service on Thursday said second wave of Covid infections has increased asset risks for Indian banks, but a severe deterioration is unlikely. It said that the second wave of coronavirus infections in India has exacerbated stress among individuals and small businesses that were hit the hardest by the initial outbreak. Still, a number of factors will prevent sharp increases in problem loans, and banks have sufficient buffers to absorb anticipated loan losses.
In the June quarter of FY24, 51 per cent of consumers who took small-ticket personal loans already had more than four credit products at the time of accessing yet another new loan, compared with just 17 per cent in the June quarter of FY20, points out Tamal Bandyopadhyay.
The Reserve Bank on Monday said asset quality of banks improved further and their gross non-performing assets (GNPA) or bad loans ratio declined to a 12-year low of 2.6 per cent in September 2024 on the back of falling slippages and steady credit demand. The RBI also flagged concern over a sharp rise in write-offs, especially among private sector banks (PVBs), which could be partly masking worsening asset quality in unsecured lending segment and dilution in underwriting standards.

Credit card spending reached Rs 2 trillion in October, a 14.5 per cent rise from September, largely driven by festival season purchases. However, the volume of outstanding credit cards increased only marginally during the same period. The spike in spending comes at a time when nearly all major credit card issuers are calibrating their growth in the segment due to visible signs of stress.

Mortgage finance remains a structural growth opportunity in India with a policy focus on affordable housing, housing shortages, low mortgage penetration, and rising incomes as drivers. Affordable Housing Finance Companies (AHFCs) serve the mass market, low-income segments, which is the least-serviced category, and to operate in this segment, the mortgage provider needs good assessment skills. AHFCs and HFCs have also been increasing exposure in other mortgage segments (loan against property, developer loans among others).
'Whether I am optimistic or pessimistic is not the issue; I am just going by the evidence available.' 'The Indian economy and financial sector are now well-placed and very resilient in dealing with any kind of spillover coming from the external world.'
Technology is rapidly reshaping industries that have long been rooted in tradition, driving a wave of innovation that is transforming everything from finance, banking, steel to manufacturing.
Defying the bearish sentiment in the markets on Monday, ICICI Bank's share price rose by 2 per cent, reaching an intraday high of Rs 1,234.4 per share on the BSE. With a 1.5 per cent gain at the close, the stock emerged as the top performer on both the BSE Sensex and the National Stock Exchange Nifty 50 indices.
Bank credit growth is expected to moderate this financial year after a robust 16 per cent estimated for last financial year, driven by strong economic activity and retail credit demand. There are three reasons for this: a statistical high-base effect given the strong growth seen last financial year, revision in risk weights by the Reserve Bank of India (RBI), and relatively slower economic activity.
Concerned over household savings moving towards alternative investment avenues, RBI Governor Shaktikanta Das on Thursday asked banks to mobilise deposits through innovative products and services by leveraging their vast branch network. "Banks are taking greater recourse to short-term non-retail deposits and other instruments of liability to meet the incremental credit demand. "This, as I emphasised elsewhere, may potentially expose the banking system to structural liquidity issues," he said.
If you opt for a term-life cover, buy separate policies to cover the loan for all the co-borrowers in a home loan for a sum assured equal to the home loan amount.

Bain Capital-backed Tyger Capital is planning to list its shares on the Indian stock exchanges by the next financial year and is targeting to grow its assets under management by four times to Rs 20,000 crore in five years from Rs 5,000 crore now, Gaurav Gupta, MD and CEO of the firm said. In an exclusive interview, Gupta said that keeping with the growing business, the finance company expects to on-board 600 people in the current financial year as it is opening 60-65 new branches for broad-basing its network in the country.

Self-employed individuals often face hurdles in buying term insurance due to financial documentation that doesn't fully reflect their earnings. This complicates underwriting.
The deal is expected to close in the January-March quarter.

'We need to be far more careful given the fact that while this is group lending, it's essentially unsecured.'

Credit Vidya helps lenders assess credit and fraud risk for thin-file and new-to-credit customers.
India's economic growth prospects should remain strong over the medium term, with GDP expanding 6-7.1 per cent annually in fiscal years 2024-2026, S&P Global Ratings said on Thursday. In a report titled 'Global Banks Country-By-Country Outlook 2024', S&P said the banking sector's weak loans will decline to 3-3.5 per cent of gross advances by March 31, 2025, on the back of structural improvement, including healthy corporate balance sheets, tighter underwriting standards and improved risk-management practices. Interest rates in India are unlikely to rise materially, and this should limit the risk for the banking industry, it added.
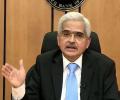
The Reserve Bank of India on Wednesday decided to keep the policy rate unchanged for the tenth time in a row but changed its stance to 'neutral' that may lead to a cut in the forthcoming policies. RBI maintained status quo despite the US Federal Reserve lowering the benchmark rates by 50 basis points last month.

High loan-to-value and high-yield buckets have reported higher delinquencies
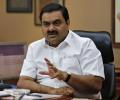
Moody's Investor Service on Tuesday said banks' exposures to Adani are not large enough to affect their credit quality materially. "While we estimate that the exposures are larger for public sector banks than for private sector banks, they are smaller than 1 per cent of total loans for most banks," it said. "Risks for banks can increase if Adani becomes more reliant on bank loans."

Moody's Investors Service on Thursday said loans to retail customers, especially those to low-income borrowers, will remain most affected due to the shock caused by the coronavirus pandemic. Despite the pandemic challenges, asset quality at Indian banks has performed better than expected at the start of the outbreak, Moody's said. "Corporate loans, in particular, have performed well because banks prior to the pandemic had largely provisioned for legacy problem loans and tightened underwriting standards," Moody's vice president and senior credit officer Srikanth Vadlamani said. Addressing an online conference organised by Moody's and its affiliate Icra, Vadlamani said an increase in non-performing loans in both public and private sector banks is subdued.
Borrowers who contribute over 40 per cent of residential unit's have greater willingness to pay.
Private banks and start-ups offer instant loans on apps as well as through ATMs.

'Accidents are unpredictable, whether it's a mishap during Diwali, a fracture during travel, or a fall in the bathroom.'
What is digital house arrest? It is a tactic cybercriminals use to confine victims to their homes and scam them, explains Tamal Bandyopadhyay.
Lenders in India, comprising banks and finance companies, anticipate robust growth in retail credit during the upcoming festival season, stretching from September to December 2023. This expectation is based on resilient demand, government initiatives, and elections in key states.
The steel-maker will now have to pay 50 basis points more on this tranche of $1 billion with a seven-year tenure.

Most borrowers of loans against property pin hopes on future cash flows from their business, but in case of failure to repay the loan, the lender can repossess the property and sell it.
Why is the RBI harsh on Paytm Payments Bank? Why did it give Rana Kapoor of Yes Bank Ltd such a long rope?Often, it's a long investigation process, but the RBI doesn't discuss this openly since that can threaten financial sector stability, explains Tamal Bandyopadhyay.
'They have since only tried to improve systems. Also, with regulatory guidance from time to time, we are in a position to assess a situation and react in time.'
For five consecutive policy reviews in 2023, the Reserve Bank of India (RBI) chose to hold rates, citing inflation threat. And when the prices did cool off a bit, it reminded all about the target to get the headline consumer price inflation at 4 per cent and the risks from food inflation. Heading into the new year, all eyes are on when RBI will cut the rates, especially after one of the Monetary Policy Committee (MPC) members stressed on the need for such an action in the face of the US Federal Reserve's guidance for easing rates.

While start-ups are making it easier to borrow, one needs to choose carefully.

'Mostly, the relief, if needed, would be for housing loans where a person has lost a job and is unable to pay his EMI or there has been a temporary salary cut.'
Every 30 seconds its website is connected to an SME for a loan, every five minutes it evaluates a loan, and every 20 minutes it disburses a loan.

'A credit line on UPI is going to make banks think about credit fundamentally as they digitise the credit process entirely.'
The country's largest housing finance company HDFC Ltd will merge with the country's largest private sector lender HDFC Bank, according to a regulatory filing. The scheme of amalgamation will be subject to various regulatory approvals, including from the Reserve Bank of India (RBI) and the Securities and Exchange Board of India (Sebi), HDFC Bank said in the filing on Monday.

The governor made it clear that the RBI is aware of what's happening and acts accordingly, but doesn't make a noise about that, points out Tamal Bandyopadhyay.

Education finance is a complex and dynamic sector. There are too many variables -- the course, the calibre of students, the universities, and the job prospects once the course is over, notes Tamal Bandyopadhyay.
